Buying in Daniel Island Park involves more than comparing home prices. HOA assessments, club memberships, insurance needs, lender charges, and South Carolina closing expenses can all shape the true cost of ownership. A clear review of the documents and estimates early in the process makes it easier to focus on the home, setting, and amenities that matter most to you.
Start With the Complete Monthly Picture
Daniel Island Park is known for refined Lowcountry architecture, landscaped streetscapes, waterfront and marsh-edge settings, golf-oriented amenities, and a location connected to the broader Daniel Island community. Homes may range from custom-built residences to townhomes and condominium-style properties, and each can carry a different ownership-cost structure. Before making an offer, it helps to look beyond the list price and build a realistic monthly and annual budget.
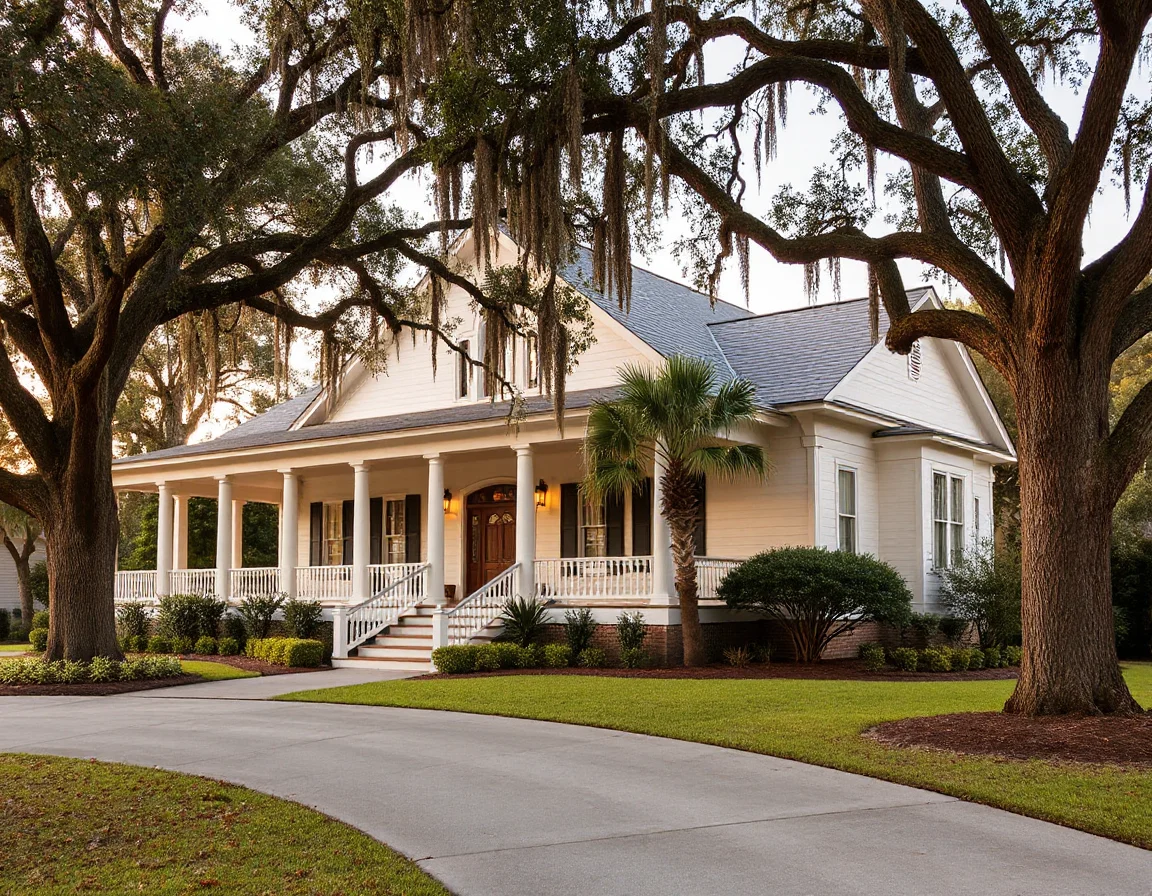
The starting point is usually the expected mortgage payment, property taxes, and homeowners insurance. From there, add the applicable property owners association assessment, any neighborhood-specific assessment, and the estimated cost of maintaining features that may not be covered by an association. A residence with a pool, dock access, extensive landscaping, or a larger outdoor living area can have different recurring costs than a lock-and-leave property with exterior maintenance included.
HOA assessments are not a one-size-fits-all figure in Daniel Island Park. They can depend on the particular neighborhood, property type, services provided, and the association’s current budget. Some assessments may support common-area landscaping, private roads, lighting, stormwater systems, community facilities, management, or reserve funding. Condominium and attached-home communities may also include building insurance and exterior upkeep in their operating budgets, while detached-home owners may carry more direct responsibility for those items.
Ask for the current HOA budget, most recent financial statements, reserve information, meeting minutes, rules, and pending-assessment disclosures before the end of the due-diligence period. Those documents often explain costs more clearly than a single monthly fee number.
It is also wise to ask whether the property is subject to more than one association. A home may have a community-wide assessment plus an additional neighborhood or condominium assessment. Confirm payment frequency, due dates, transfer charges, resale-package fees, and whether any special assessment has been approved or discussed. The goal is not simply to identify today’s fee, but to understand what that fee covers and how the association plans for future repairs or improvements.
Amenities, Clubs, and Access: Confirm What Is Included
One of the appealing parts of ownership in and around Daniel Island Park is proximity to outdoor spaces, walking and biking routes, water views, golf facilities, tennis and pickleball opportunities, dining, and community programming. However, access is not always automatically included with the purchase of a home. Certain facilities may require a separate membership, initiation charge, recurring dues, reservations, or guest fees.
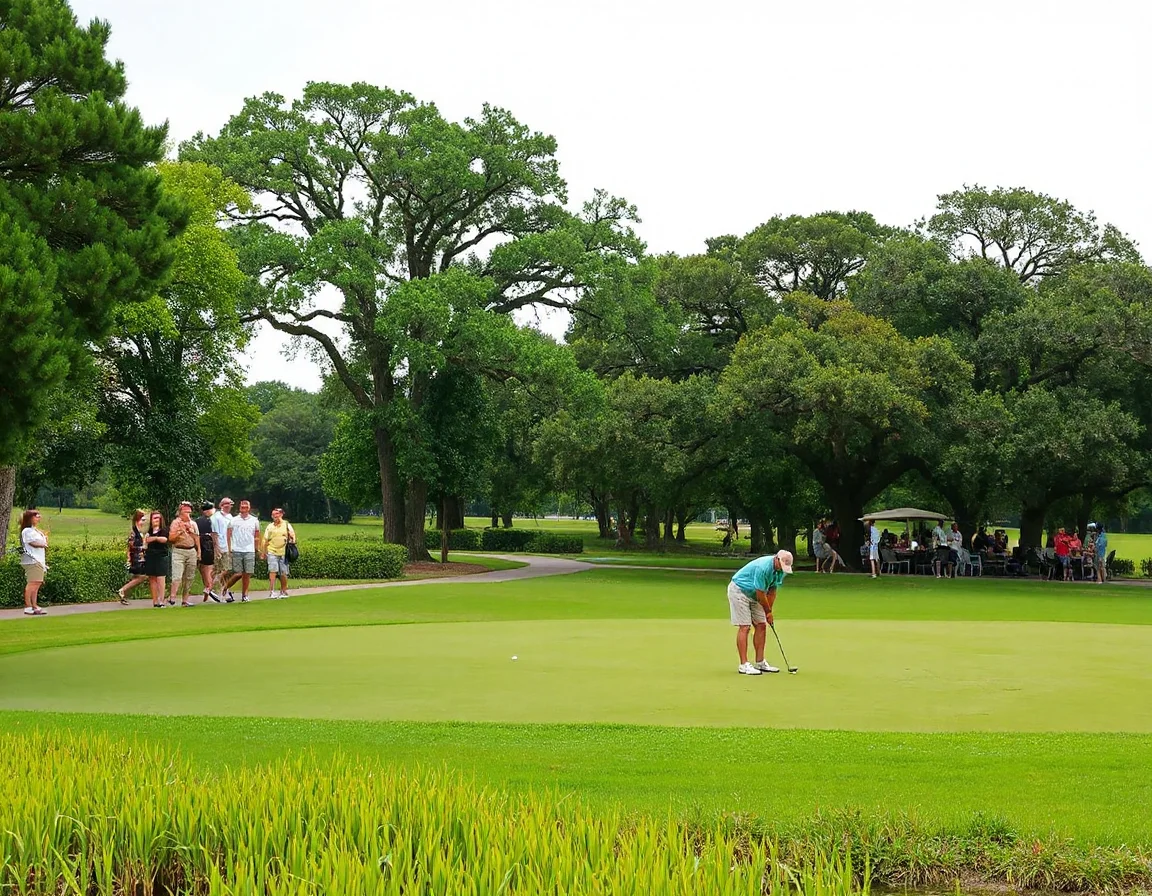
When evaluating a property, request a written outline of available amenities and the requirements for using them. If country club access is important, confirm the current membership categories, dues, initiation requirements, waitlist status if applicable, dining minimums, and whether membership transfers with the property. Rules and fees can change, so current information from the club or association is more reliable than prior marketing materials or informal recollections.
For waterfront or marsh-adjacent homes, the due-diligence conversation should also include insurance and maintenance. Flood insurance requirements can vary by the home’s location, elevation, loan terms, and insurer. A buyer may also want to review the age and condition of roofs, exterior materials, seawalls, docks, bulkheads, irrigation systems, and drainage features. These are practical ownership details that can influence both the initial purchase decision and long-term budgeting.
Walk through the neighborhood at more than one time of day if possible. Notice roadway access, parking arrangements, sidewalks, tree cover, open-space views, construction activity, and the routes to daily destinations. This kind of observation complements the formal documents and helps turn a listing description into a more complete understanding of the property.
Closing Costs in South Carolina: Plan Before the Offer
Closing costs are the other major piece of the financial picture. In South Carolina, real estate closings are typically handled through an attorney, and buyers commonly receive a Loan Estimate from their lender followed by a Closing Disclosure before settlement. These documents are useful tools for comparing expected charges, but they should be read alongside the contract, inspection findings, association disclosures, and insurance quotes.
Buyer expenses can include lender origination or underwriting fees, appraisal charges, credit and verification services, title examination, title insurance, attorney fees, recording costs, prepaid interest, initial escrow deposits, and insurance premiums. The precise total depends on the price, loan type, down payment, closing date, lender, negotiated contract terms, and whether the property has assessments or association-related transfer requirements.
Property taxes deserve special attention. At closing, taxes and association dues may be prorated between the buyer and seller based on the settlement date and local billing cycle. South Carolina property-tax treatment can also change after a purchase depending on how the property will be used and whether the owner qualifies for a particular assessment classification. An attorney, lender, and tax professional can help explain the documents relevant to an individual transaction.
A strong offer strategy accounts for these costs from the outset. Rather than focusing only on the purchase price, consider how earnest money, financing contingencies, inspection allowances, requested repairs, closing-date timing, and any seller contribution affect the cash needed to close. A pre-approval is useful, but a full conversation with the lender about reserves, insurance, and final funds can prevent surprises later.
Due Diligence That Supports a Confident Decision
In a competitive luxury market, it can be tempting to move quickly. Thoughtful preparation makes it possible to act decisively without skipping important questions. Review the seller disclosure, inspection reports, survey, insurance estimates, HOA package, club information, and lender figures as a connected set of documents. Each one reveals part of the ownership story.
For homes with custom finishes or historic-inspired details, consider specialized inspections when appropriate. Roof systems, HVAC equipment, plumbing, electrical panels, fireplaces, pools, docks, retaining features, and moisture management can warrant additional review depending on the property. The purpose is not to search for perfection; it is to understand condition, expected maintenance, and possible near-term investments.
Working with a local real estate professional can make the process more manageable, particularly when a purchase includes association documents, waterfront considerations, club questions, and several service providers. Charleston Realty and Jayson Wingfield can help coordinate the information needed for a well-organized search and purchase process while keeping the focus on your goals and timeline.
Search Daniel Island Park listings
A Better Budget Creates More Room to Enjoy the Home
The most satisfying home purchase is rarely about one number alone. It is about aligning the purchase price, monthly obligations, amenities, upkeep expectations, and closing funds with a clear plan. Daniel Island Park offers a distinctive blend of Lowcountry landscape, polished residential design, and access to a broad range of recreation and services; careful due diligence helps you experience those advantages with fewer financial unknowns.
Before submitting an offer, assemble a property-specific worksheet with the proposed payment, taxes, insurance, HOA assessments, club costs if desired, utility estimates, anticipated maintenance, and projected closing costs. Updating that worksheet as new information arrives gives you a practical decision-making tool—and a more confident path from contract to closing.