
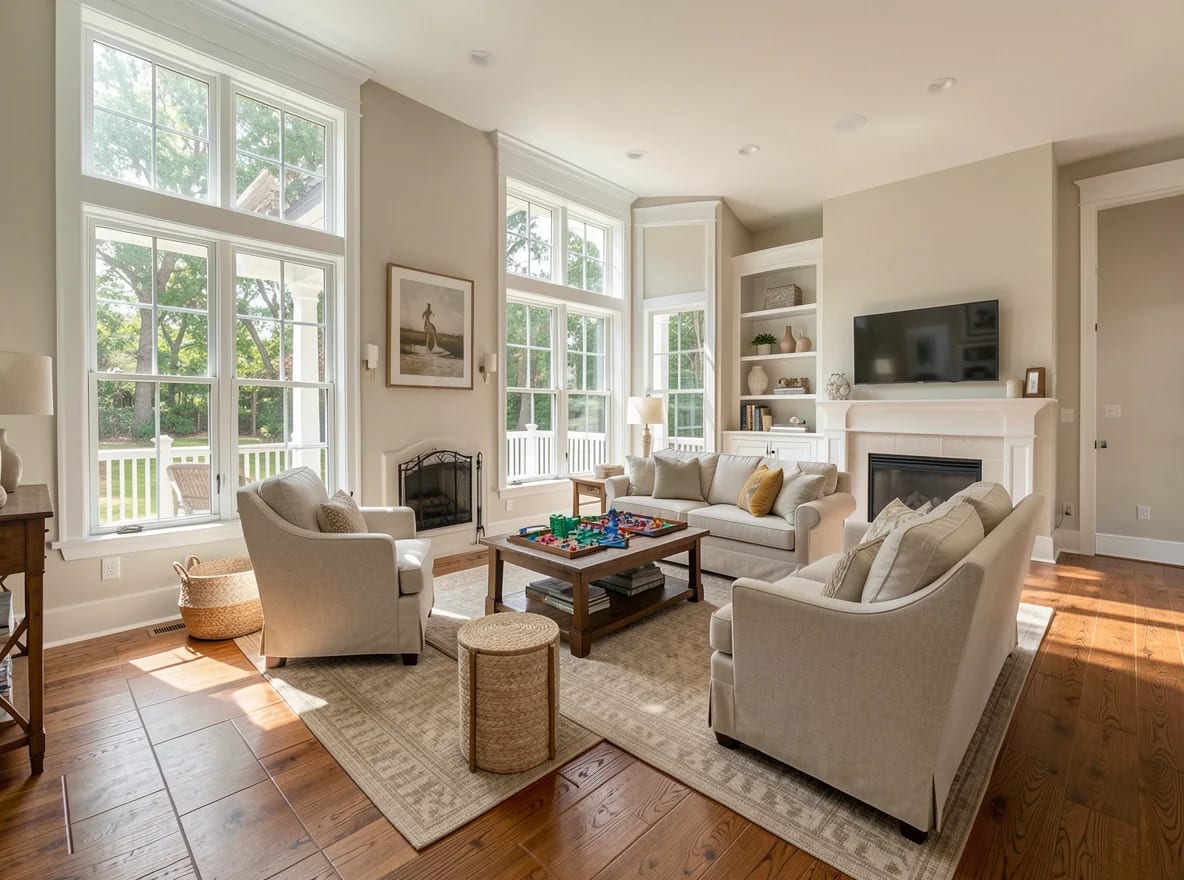
Buying your first home in I’On is easier to navigate when you understand the numbers before you make an offer. From mortgage preapproval and insurance quotes to inspections and the closing table, this guide lays out the decisions and deadlines that can shape your purchase.
Start with the full cost of ownership
In I’On, a neighborhood in Mount Pleasant, streets, porches, lakes, and gathering spaces give the community a distinctive Lowcountry character. Before you fall for a particular property, take time to understand what it will cost to buy and own it. The listing price is only the starting point: financing, insurance, taxes, association charges, and maintenance all belong in your budget.
Begin with a monthly payment range that leaves room for your other priorities. A mortgage payment commonly includes principal and interest, and your lender may also collect money each month for property taxes and insurance through an escrow account. Add any homeowners association dues separately unless they are included in the lender’s estimate. Utilities, landscaping, repairs, and future improvements deserve a place in the plan, too.
Next, consider how much cash you want available at closing and afterward. Your down payment is one part of the picture; lender charges, prepaid insurance, taxes, inspections, and legal fees can add to the amount needed. Keeping a reserve for unexpected expenses can be just as important as assembling the funds to purchase.
Ask for an insurance quote and current association information early. Both can affect the monthly cost of an I’On home even when two properties have similar asking prices.
Property taxes also require a closer look. A seller’s current bill may not reflect what you will pay after a purchase, and an eligible owner-occupied residence may qualify for South Carolina’s legal-residence assessment rate. Ask the county assessor about eligibility, application requirements, and a property-specific estimate rather than relying on the seller’s bill.
Get preapproved and compare financing
A mortgage preapproval gives you a clearer view of your potential borrowing range before you begin making offers. A lender typically reviews your income, assets, debts, and credit information, then issues a letter based on the information available. Preapproval is useful, but it is not a final loan commitment; the home, appraisal, title, and updated financial documents may still need review.
Talk with more than one lender and request comparable estimates. Look beyond the interest rate to the annual percentage rate, lender fees, discount points, down payment, mortgage insurance, and whether the rate is fixed or adjustable. Ask how long a rate lock lasts and what could happen if closing is delayed. A lower advertised rate is not necessarily the least expensive choice once fees are included.
Conventional loans, FHA loans, VA loans, and other programs have different qualification and property requirements. Some first-time buyer or assistance programs may also be available, subject to funding, income, purchase-price, location, and other rules. Ask lenders about current options and whether a particular property and loan amount qualify; do not assume assistance can be combined with every mortgage.
Learn how to choose a mortgage lender
Documents worth gathering
Requirements vary, but a lender may request recent pay information, tax documents, bank statements, identification, and explanations for large deposits. If funds are coming from a gift or the sale of another asset, ask how to document the source. Once you are under contract, check with your lender before taking on new debt, changing jobs, or moving substantial sums between accounts.
Evaluate the home as well as the neighborhood
As you compare properties, look closely at the features that matter to your daily routine: layout, outdoor space, parking, storage, and proximity to the places you visit. I’On’s location also makes it useful to explore Mount Pleasant’s dining, parks, and routes toward Charleston. Visit at different times of day and test your own typical trips rather than relying on estimated travel times.
For each home, request available seller disclosures and review the age and condition of major components such as the roof, HVAC system, windows, and drainage. A professional home inspection can help identify concerns, but it may not cover every system or hidden condition. Depending on the property, you may also want specialized inspections for pests, moisture, structural issues, or other specific questions.
Review the homeowners association’s governing documents, dues, rules, and any available information about planned assessments. Ask which amenities are included and whether access to any club or recreational facility requires a separate membership or fee. If you hope to renovate, add fencing, or make exterior changes, find out what approvals may be required before assuming your plans are possible.
Because coastal South Carolina properties can face wind and water exposure, obtain property-specific homeowners, wind, and flood insurance information. Flood risk can exist outside high-risk mapped zones, and lender requirements may differ by location and loan. Ask your insurance professional about deductibles, coverage limits, exclusions, and whether elevation or prior claims information could affect a quote.
Make an offer with a plan for deadlines
When you find the right property, work with your real estate agent to assess comparable sales, the home’s condition, and current competition. The offer price matters, but so do the proposed closing date, earnest money, financing terms, inspection provisions, and other contingencies. Your agent can explain how the contract addresses these items and help you decide which terms match your circumstances.
Once the offer is accepted, keep a written calendar of every deadline. Earnest money is generally deposited according to the contract and is typically credited toward the purchase at closing, subject to the contract’s terms. Inspection, repair negotiations, financing, appraisal, and any association-document review can each have their own timelines. Missing a deadline may affect your options, so ask questions before a date passes.
An appraisal and a home inspection serve different purposes: the appraisal supports the lender’s valuation decision, while an inspection focuses on the property’s condition.
If the appraisal comes in below the agreed price, discuss your options promptly with your agent and lender. Depending on the contract and financing, possibilities may include renegotiating, contributing additional cash, challenging factual errors in the appraisal, or exercising an applicable contingency. None is automatic; your contract and lender’s requirements control the next steps.
Prepare for the South Carolina closing table
In South Carolina, a licensed attorney is generally involved in closing a residential real estate transaction. The closing attorney coordinates legal aspects of the transfer, including title work and preparation or review of closing documents. Ask early who will handle the closing, what fees to expect, and how title insurance options will be presented.
Your lender will continue underwriting the loan while the attorney and other parties work toward closing. Respond quickly to document requests, confirm your insurance coverage, and avoid assuming the loan is final until the lender gives its approval. For most mortgages, you must receive a Closing Disclosure at least three business days before consummation; review the figures and ask about changes from your earlier Loan Estimate. Certain changes can trigger a new waiting period.
Before closing, arrange a final walk-through under the terms of your contract. Check that the property’s condition is consistent with the agreement, that negotiated work has been completed, and that included items remain. Confirm the amount needed to close with the attorney, and independently verify wiring instructions using a trusted phone number. Wire fraud is a real risk, so never rely on a last-minute email change alone.
On closing day, bring the identification and funds requested by the closing office, review the documents carefully, and ask about anything you do not understand. After signing, funding, and recording as applicable, you can move forward with the handoff of keys. With a clear budget, a responsive lending team, and attention to the contract’s milestones, you can approach your first purchase in I’On with a stronger understanding of both the opportunity and the obligations.